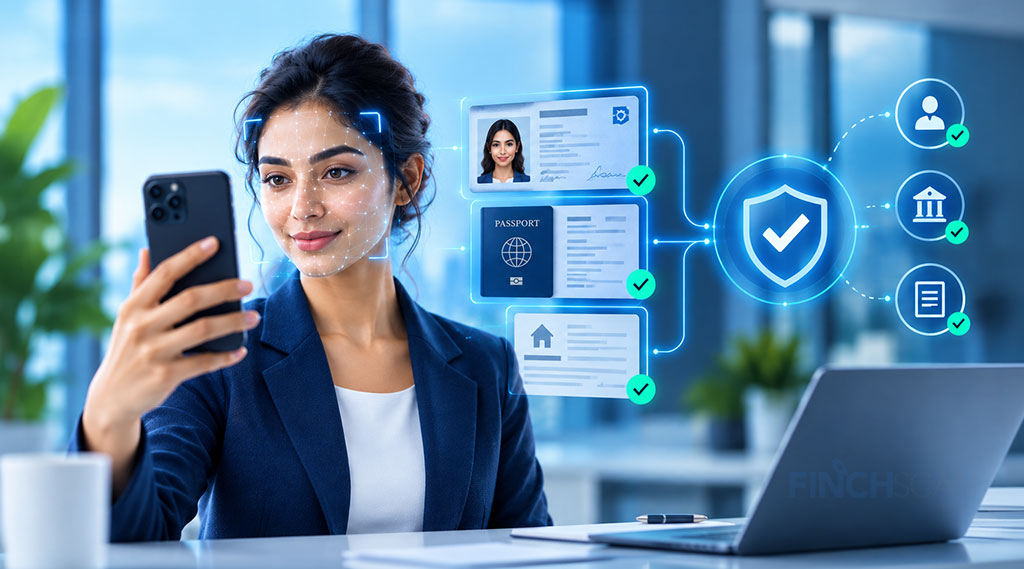
Quick Answer: Digital KYC is the process of verifying a customer’s identity entirely online, using tools such as document capture, optical character recognition, biometric liveness detection, and real-time database cross-checks. It allows a business to onboard a customer remotely, without a branch visit or a paper form, while still meeting the same identity and risk requirements as a manual process.
Know Your Customer (KYC) does not have to happen across a desk. For most fintech companies, banks, and other regulated businesses, it happens on a customer’s phone or laptop, in a few minutes, before the customer ever speaks to anyone at the business. This guide looks specifically at how that digital process works, the technology behind it, and where it differs from a manual, in-person approach. For a broader introduction to KYC itself, see our guide to What Is KYC.
What Makes KYC “Digital”?
Traditional KYC generally involves a customer visiting a branch or office, presenting physical documents, and having those documents checked manually by a member of staff. Digital KYC moves every part of that process online: the customer submits documents through a mobile app or browser, verification runs through automated tools rather than a manual reviewer, and the result is typically available in minutes rather than days.
The shift to digital does not lower the bar for verification. It changes how that bar is met.
The Digital KYC Process, Step by Step
1. Document Capture
The customer photographs or uploads an identity document, such as a passport, national ID, or driving licence, directly through a mobile app or web browser. Modern capture tools check image quality in real time, flagging glare, blur, or cropping issues before the document is submitted, rather than rejecting it after the fact.
2. Optical Character Recognition (OCR)
Once captured, the document’s data is extracted automatically rather than typed in manually. OCR reduces both the effort required from the customer and the risk of transcription error, and it gives the verification system structured data to check against other sources.
3. Biometric Verification and Liveness Detection
The customer takes a live selfie or short video, which is matched against the photo on their identity document. Liveness detection is what separates this from a simple photo match: it is designed to confirm that a real person is present at the time of onboarding, rather than a printed photo, a video replay, or a deepfake.
4. Real-Time Database and Watchlist Cross-Checks
The extracted data is checked against government or third-party databases to confirm the document is genuine and the details are consistent. This step can run in parallel with sanctions, PEP, and adverse media screening, so identity verification and AML screening happen within the same workflow rather than as separate steps.
5. Automated Risk Scoring
Based on the verification results and screening outcome, the customer is assigned a risk level. Low-risk applicants can typically proceed immediately, while higher-risk applicants may be routed to a human reviewer or asked for additional information.
6. E-Signatures and Digital Consent
The customer reviews and accepts terms, privacy notices, and other disclosures electronically, completing the onboarding step end to end without printing or posting anything.
7. Ongoing Digital Monitoring
Digital KYC does not end at onboarding. Automated monitoring can flag new sanctions designations, PEP status changes, or adverse media after the customer has been onboarded, without requiring a manual re-check of every customer on a fixed schedule.
Digital Identity Verification Methods
Not every digital verification step relies on the same underlying method. In practice, most solutions combine several:
- Document-based verification checks the authenticity of the identity document itself, including security features, formatting, and consistency between fields.
- Biometric verification compares a live selfie or video against the document photo, using liveness detection to rule out spoofing and identity fraud.
- Database or registry-based verification confirms the document or individual against an authoritative source, such as a government registry or credit bureau, rather than relying on the document alone.
- Knowledge-based verification asks the customer to confirm information that only they should know, though this method is generally used as a supplementary check rather than a primary one, since it is more vulnerable to social engineering.
Most reliable digital KYC workflows layer two or more of these methods together, rather than depending on a single check.
| Feature | Traditional KYC | Digital KYC |
|---|---|---|
| Verification location | In person, typically a branch or office | Remote, via mobile app or browser |
| Document handling | Physical documents, manual review | Photographed or uploaded, automated review |
| Data entry | Manual, by staff or customer | Automated extraction (OCR) |
| Fraud detection | Visual inspection by a trained reviewer | Liveness detection, database cross-checks, document forensics |
| Typical turnaround | Hours to days | Minutes |
| Scalability | Limited by staff availability | Scales with application volume |
Neither approach is inherently more rigorous than the other. The difference is in how consistently the checks are applied and how quickly a decision can be reached.
What Documents Are Needed for Digital Verification?
Digital verification generally works best with documents that include a photograph and machine-readable security features, such as:
- Passports
- National identity cards
- Driving licences (where accepted as a primary ID document)
Some digital workflows also request a secondary document, such as a utility bill, bank statement or region-specific documents to confirm an address, though this depends on the business’s risk-based requirements and applicable regulations.
Benefits of Digital Onboarding
- Speed. Verification that once took days can often be completed in minutes.
- Consistency. Automated checks apply the same standard to every applicant, rather than varying by reviewer.
- Fraud resistance. Liveness detection and database cross-checks catch certain fraud patterns, such as photo spoofing, that a manual visual check can miss.
- Scalability: A digital process can handle a surge in applications without a proportional increase in reviewing staff.
- Customer experience. Applicants complete onboarding from their phone, on their own time, without visiting a branch.
Common Challenges in Digital KYC
Digital KYC is not without its own risks, and a responsible implementation should account for them rather than assume automation solves everything:
- Spoofing and deepfakes. As liveness detection improves, so do attempts to defeat it. Verification providers need to update detection methods on an ongoing basis, not treat it as a solved problem.
- Document fraud. Forged or manipulated documents can sometimes pass an automated check if it is not secure enough, which is why document forensics and database cross-checks matter alongside OCR.
- Regulatory variation. Not every jurisdiction accepts fully digital identity verification for every use case, and requirements can differ by document type, customer type, and risk level.
- Balancing friction and security. Adding more verification steps can reduce fraud but also increase drop-off, so the workflow needs to be risk-based rather than maximal by default.
How Finchscan Supports Digital KYC
Finchscan brings document capture, OCR, biometric liveness detection, real-time database checks, and risk scoring together in a single digital onboarding workflow, so identity verification and AML screening do not run as separate, disconnected processes.
Curious how this would work against your own applicant flow?
Final Thoughts
Digital KYC does not replace the principles behind Know Your Customer process. It changes how those principles are applied, replacing manual document review and in-person checks with automated capture, biometric verification, and real-time screening. For businesses onboarding customers remotely, the technology matters as much as the policy, since a strong process depends on both being designed together.
For a broader introduction to KYC itself, see our guide to What Is KYC. To see how Finchscan brings digital identity verification and AML screening into one workflow, book a demo with our team.
Frequently Asked Questions About KYC
Is digital KYC as secure as in-person verification?
When implemented with liveness detection, document forensics, and database cross-checks, digital KYC can meet or exceed the reliability of a manual visual check, which depends heavily on the individual reviewer’s training and attentiveness.
Can digital KYC detect deepfakes?
Liveness detection is specifically designed to distinguish a live person from a photo, video replay, or synthetic media, though detection methods need continuous updates as spoofing techniques evolve.
Is digital KYC legally accepted everywhere?
Acceptance varies by jurisdiction, industry, and document type. Businesses should confirm which digital verification methods are recognised under the regulations that apply to their specific market before relying on them exclusively.
How long does digital verification typically take?
Most digital KYC checks complete within minutes, though cases requiring Enhanced Due Diligence or manual review will take longer.
What happens if digital verification fails?
A failed automated check does not necessarily mean fraud. It is typically routed to re-KYC or manual review, where a human reviewer examines the flagged document or biometric match before a final decision is made.